
AI in Wealth Management: Use Cases, Risk, and Generative AI
Generative AI is revolutionizing wealth management, boosting expertise, efficiency, personalization, and decision-making. Discover how data and technology partnerships drive growth and competitive advantage for modern firms.
- AI Integrations
September 28, 2026
 AI Overview
AI in wealth management combines predictive models, generative AI, and automated decision systems to support advisor research, client personalization, risk profiling, suitability checks, compliance, and portfolio communication. Strong implementations pair unified client data with model governance, explainability, human review, and audit trails, so firms can scale advisory workflows without turning regulated decisions into black boxes.

Wealth management has for a long time struck a balance between human judgment and data, as well as between efficiency and trust. That balance is now under measurable strain. Capgemini’s World Wealth Report 2026, based on a January 2026 survey of 6,510 high-net-worth individuals across the Americas, Europe, Asia-Pacific and the Middle East, found that only 17% describe their advisory experience as seamless and personalized, and 42% have to restate their goals and preferences more than once to the same firm. Meanwhile, Cerulli Associates projects that $124 trillion in US wealth will change hands through 2048, most of it to heirs; the current service model already struggles to cover it individually.
Those two facts explain why artificial intelligence in wealth management stopped being an innovation-team topic: the gap between client expectations and what an advisory team can deliver at current cost is not closing through hiring. This article sets out what firms are actually doing with AI wealth management programs today — where the technology is genuinely deployed, where the evidence is thinner than the marketing, what supervisors expect, and what foundations have to exist first.
How AI is Transforming Wealth Management
AI in wealth management is changing the business in two ways: it is reducing the amount of operational work associated with giving advice, and it is altering the extent of what a firm can know about a client prior to giving that advice. The first of these relates to capacity, while the second is a matter of suitability and governance and is the more difficult one.
From Predictive Analytics to Generative AI in Wealth Management
For nearly the entire previous decade, applied machine learning in the field has been concerned with prediction and classification — specifically with anomaly detection, propensity models, churn scoring, and portfolio risk analytics. These systems took structured historical data as input and outputted numbers.
Generative models have affected both the input and the output since they take in unstructured material — such as meeting transcripts, research notes, fund documentation, and regulatory filings — and then generate text, for example a portfolio summary, an explanation of a drawdown, or a draft suitability rationale. Most friction in an advisory business is documentary rather than analytical, and Capgemini’s 2026 research quantifies it: 41% of relationship manager time goes to operational tasks, leaving limited capacity for proactive client engagement. Generative AI for wealth management attacks that 41%.
What is Actually Driving Adoption
Three pressures are driving adoption of generative AI in wealth management and its predictive predecessors.
Client expectations have been reset by other industries. In LSEG research with ThoughtLab (October 2024), covering 2,000 investors globally and senior executives at 250 wealth management firms across Asia-Pacific, Europe, the Middle East and North America, 68% of investors said they expect their digital experiences to match those of leading technology companies — a benchmark set by consumer software, not by competitors.
Advisor capacity is constrained and worsening. McKinsey’s US wealth management in 2035 analysis (January 2026) estimates that around 40% of US advisors will retire within a decade — a shortfall of roughly 100,000 professionals.
The economics have been modeled, not proven. The same analysis puts task-level automation at up to 20 to 30 percent of advisor time saved, and a separate McKinsey study of the asset management industry estimates that AI, generative AI and agentic AI together could deliver efficiencies equivalent to 25 to 40 percent of a manager's total cost base (July 2025).
That third point needs qualification, because it is where most writing on this topic overreaches: these are consultancy models, not measured outcomes. The September 2026 Oliver Wyman and Morgan Stanley report Breaking from the Pack found that 55% of firms have integrated AI into at least one part of the investment process and another 27% are piloting — but also that half of asset and wealth management CEOs report either no AI-driven cost savings or that it is still too early to assess them. No independent controlled study of advisor productivity gains from AI copilots has been published. Treat published efficiency figures as ranges to test internally, not benchmarks already achieved elsewhere.
AI in Wealth Management: Use Cases and Real-World Examples
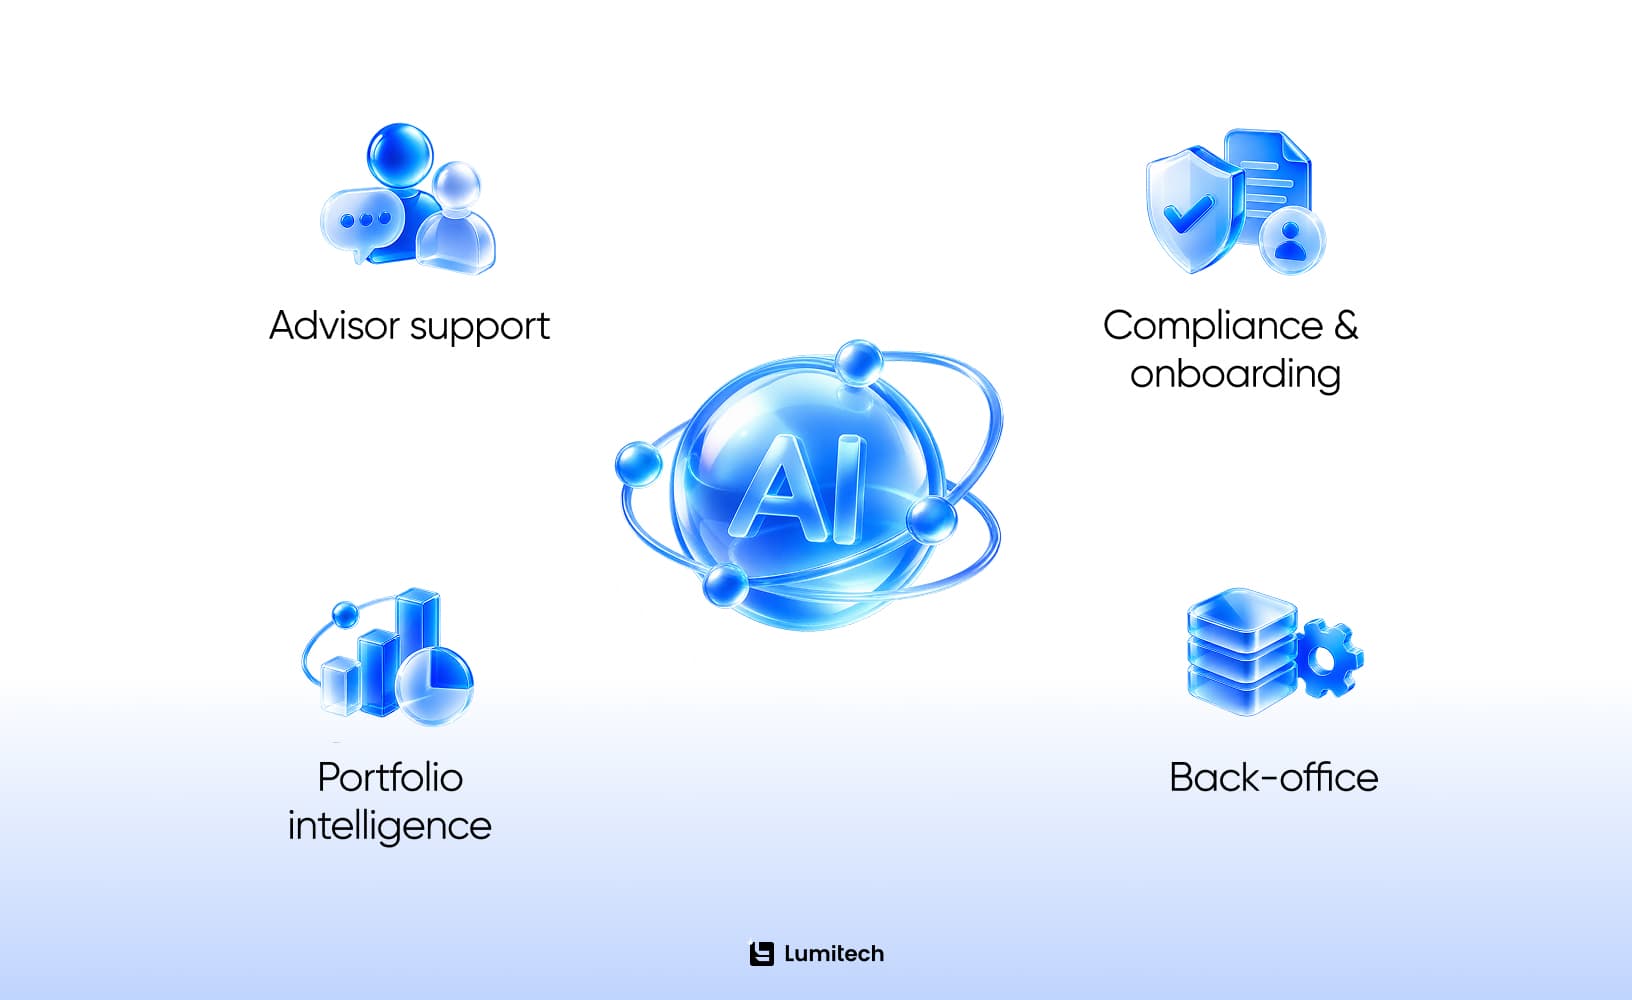
The AI use cases in wealth management genuinely in production cluster around four areas: advisor support, compliance and reporting, portfolio intelligence, and back-office operations. Client-facing autonomous advice is not among them, for regulatory rather than technical reasons. The clearest AI in wealth management examples come from large firms that have published what they deployed and when, making them verifiable in ways vendor case studies usually are not.
Advisor Copilots and Client Engagement
The most widely deployed application of generative AI for wealth advisors is the meeting lifecycle. Morgan Stanley’s AI @ Morgan Stanley Debrief, launched in June 2024, generates meeting notes with client consent, drafts follow-up emails for advisor review, and saves summaries to Salesforce; in the same announcement, the firm stated that 98% of its Financial Advisor teams had adopted its earlier AI @ Morgan Stanley Assistant. Merrill Wealth Management and Bank of America Private Bank launched a comparable AI-powered meeting journey in March 2026, which the bank says can save up to four hours per meeting.
Read these carefully: they report adoption, coverage, and estimated time saved, not independently measured performance, and the 98% attaches to the Assistant chatbot rather than to Debrief. Although the tooling meets the usability requirements in a regulated environment, this does not prove that it has a revenue impact. Copilots establish their value by reducing the amount of documentation that needs to be reviewed, not by giving better advice.
Compliance, Onboarding and Regulatory Reporting
Compliance is where AI solutions for wealth management transition from offering convenience to becoming economically viable, since this type of work is characterized by its high volume, adherence to rules and the need to produce evidence. Generative models extract obligations from regulatory text, draft first-pass reports and summarize case files for sign-off. Alongside them sits the longest-established use of machine learning in wealth management: screening and surveillance models that flag anomalies and sanctions matches earlier than rules alone. In onboarding, KYC automation compresses identity verification, screening and risk scoring into a logged workflow — which matters less for the speed than for the audit trail it leaves behind.
None of this transfers accountability. FINRA’s Regulatory Notice 24-09 (27 June 2024) states that supervision under Rule 3110 and the content standards of Rule 2210 apply to generative AI and large language model tools as they do to any other technology, and that Gen AI use could implicate virtually every area of a firm’s regulatory obligations. An AI-drafted compliance document is a firm communication with a named supervisor attached.
Portfolio Intelligence and Client Communication
In investment workflows, the safest pattern for generative AI in wealth management is a translation layer over analytics that already exist and are already validated. BlackRock’s Aladdin Wealth Auto Commentary, launched in October 2025 with Morgan Stanley’s Portfolio Risk Platform as first implementer, illustrates it: the platform computes the risk analytics and the model summarizes hundreds of data points into readable commentary. It is the narrative that is generated, not the numbers.
That separation matters. If a model produces both the analysis and the explanation together, then a hallucinated figure and a plausible justification appear as a single output and are difficult to challenge. But if the model only provides an explanation for a computed result, the figure remains independently verifiable.
Back-Office Automation in Wealth Management
Behind advisory sits reconciliation, audit preparation, document review, client reporting and knowledge management — the layer where AI automation for wealth management has the least regulatory exposure and the clearest payback.
Bank of America disclosed in April 2025 that more than 90% of its employees use Erica for Employees, its internal support assistant, and that IT service desk call volume fell by more than 50%; separately, developers using a generative AI coding tool reported efficiency gains of over 20%. UBS reports on its innovation and AI page that its internal assistant, Red, is deployed to around 100,000 employees and saves them an average of 80 minutes per week.
The most credible efficiency figures currently available in the field of wealth management and in related banking sectors are those which relate to the firm’s internal operations, since these operations can be directly monitored by the company. Moreover, these figures are self-reported and refer to support and engineering work rather than to advisory services.
Every use case above depends on one precondition: the model needs a correct, current, permissioned view of the client. When that view is missing, the failure surfaces first — and most expensively — in risk profiling.
Risk Profiling and Suitability with AI
Risk profiling is where AI in wealth management makes its most defensible contribution and carries its highest liability. A traditional profile is a questionnaire completed once and revisited annually. It records what a client says about risk in a calm room, which poorly predicts what the same client does during a drawdown.
Behavior as a Second Input
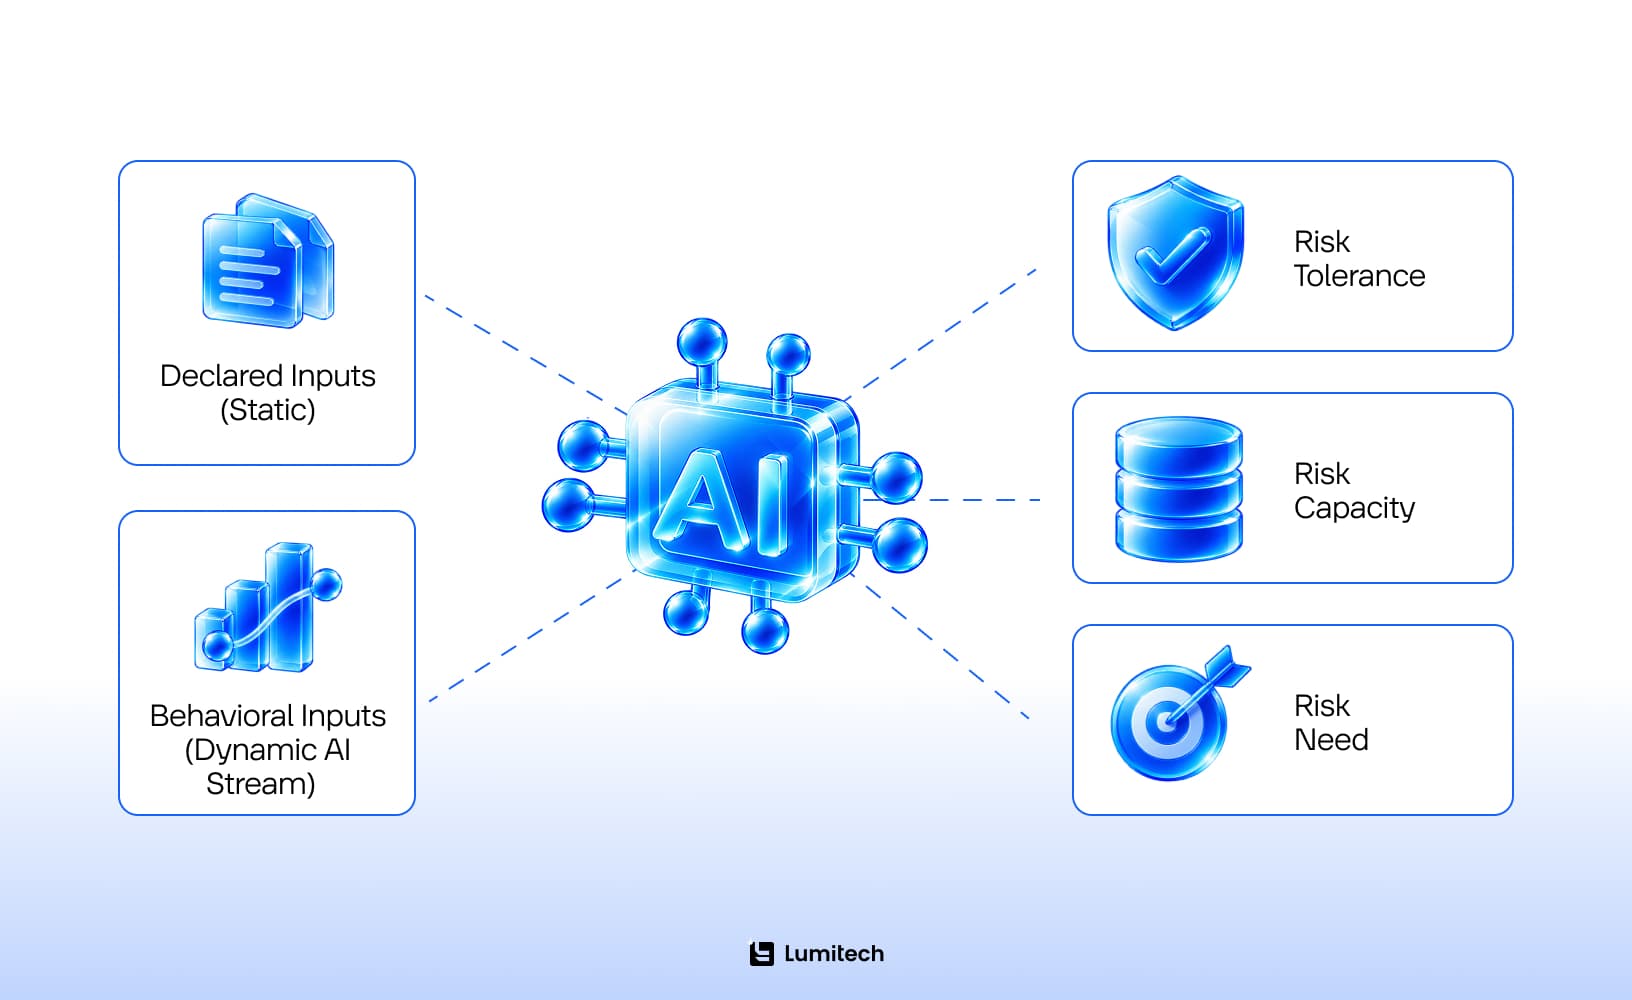
AI for wealth management risk assessment adds a behavioral layer on top of the declared one: trading activity during volatility, changes in contribution levels, portfolio adjustments after market stress. The value lies in the gap between the two. A client who scores “balanced” on a questionnaire but sells their equity during the first 5% drawdown has a profiling issue that the questionnaire cannot detect.
Done properly, this also separates three dimensions firms routinely collapse into one score:
Risk tolerance — psychological readiness to accept volatility
Risk capacity — financial ability to absorb loss without compromising objectives
Risk need — the return actually required to meet stated goals
Modeled separately, these make recommendations materially more accurate: a client can be tolerant but low-capacity, or high-capacity with no need to take risk at all. Collapsing them into one score hides the mismatches suitability rules exist to catch.
Continuous profiling extends the logic over time, replacing the annual review with monitored signals — income changes, large transactions, life events, shifts in portfolio behavior. Every change carries a timestamp and a trigger, so suitability stops being a periodic attestation and becomes a process with evidence attached to each state change.
Where Profiling Models Go Wrong
Three failure modes recur, and all are governance rather than modeling failures.
Treating model output as final truth. A risk score is an input to an advisor’s judgment, not a substitute. ESMA’s public statement on AI and investment services (30 May 2024) is explicit that MiFID II requirements — organizational, conduct of business, and above all the duty to act in the client’s best interest — apply regardless of whether AI is used, and names algorithmic bias and data quality, opaque decision-making, overreliance by firms and clients, and privacy and security as the principal risks.
Complexity that obscures the decision. A model an advisor cannot interrogate cannot be effectively challenged, and a recommendation that cannot be challenged cannot be defended to a regulator.
Conflicts of interest embedded in the objective function. If a recommendation model is optimized for engagement or asset gathering rather than client outcome, the conflict lives in the code rather than in a disclosure. The SEC’s proposed rule on conflicts in predictive data analytics was withdrawn on 12 June 2025, so no AI-specific US rule covers this — but fiduciary and Reg BI obligations are unchanged, and the SEC’s 2026 examination priorities (17 November 2025) state that examiners will assess whether firms have adequate policies to supervise their use of AI and will review registrant representations about AI capability for accuracy. That second clause binds marketing as tightly as compliance: the SEC’s first AI-washing actions, against Delphia and Global Predictions in March 2024, concerned overstated claims, not defective models.
Making Suitability Defensible
A suitability decision can be considered defensible if the company is able to reconstruct the reasons for it: namely, which data was used, which rules were applied, why certain alternatives were rejected, which version of the model generated the scores, and who finally approved the result.
A hybrid design supports this: the system forms the recommendation and flags risks, and the advisor retains what supervisors call the right to effective challenge — to question, modify, or reject the output, with the deviation and its reasoning recorded. One principle runs against product instinct: AI solutions for wealth management should narrow the choice set and explain the trade-offs, not expand it. Three well-reasoned scenarios beat thirty ranked options — and reconstruction is only possible if the system was built to explain itself.
Explainable AI, Governance, and Human Oversight
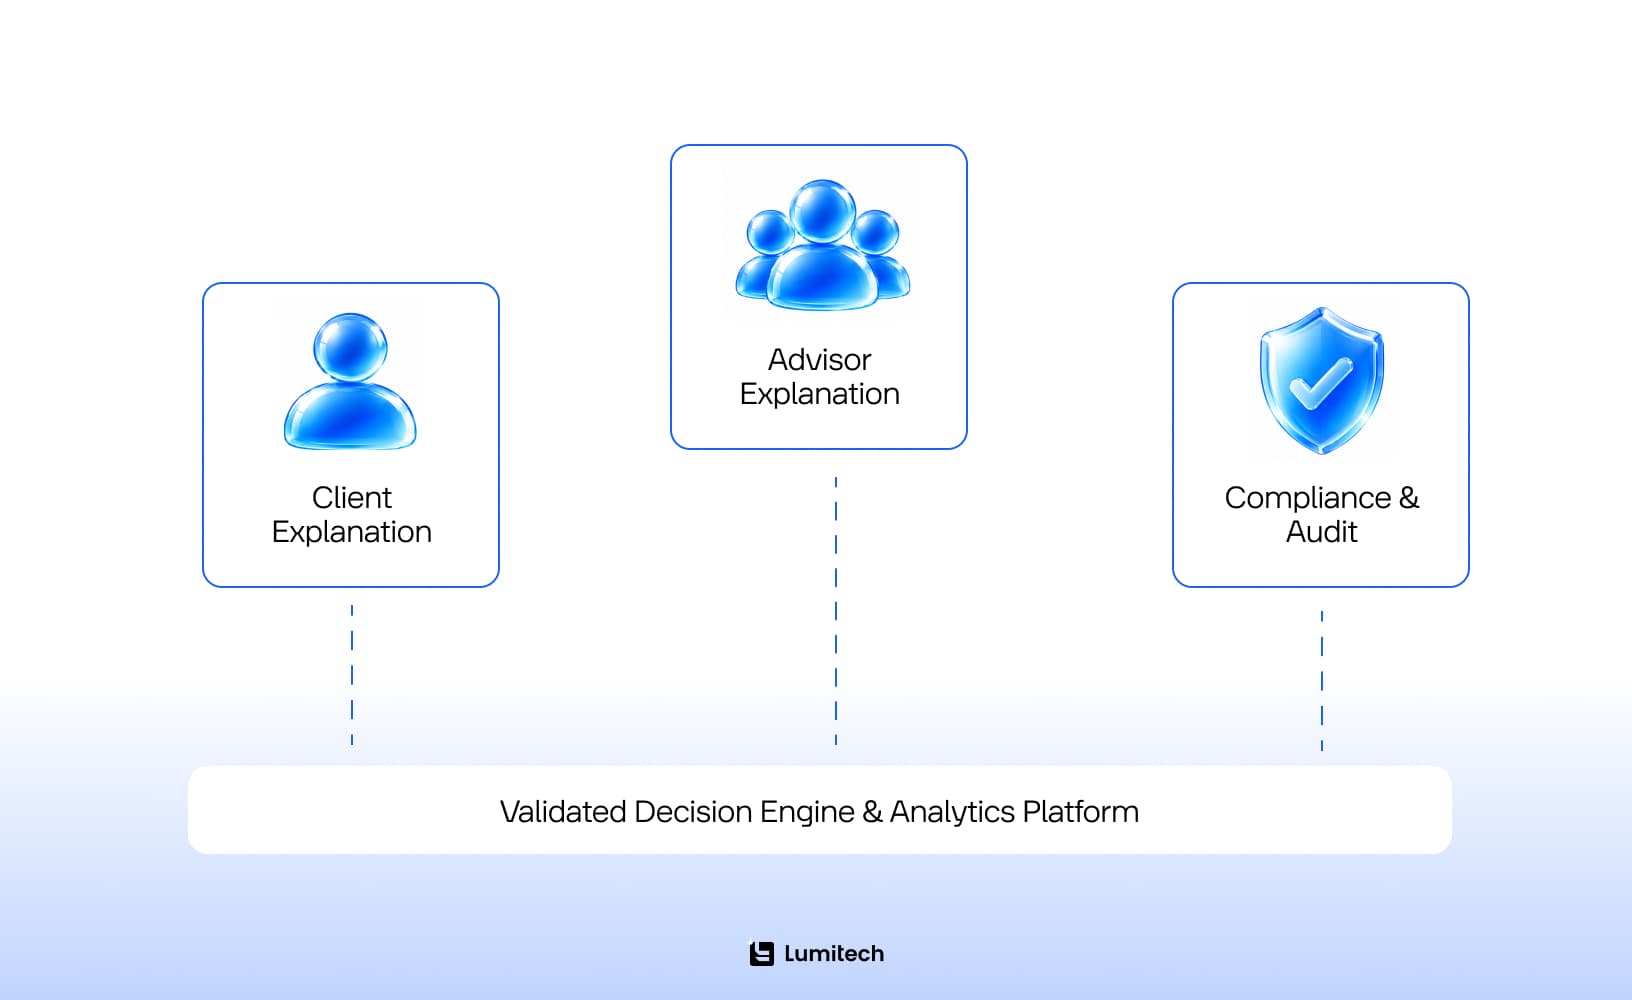
In regulated advice, explainability is not a model feature but a property of the system around it — and a single explanation cannot serve everyone who needs one. Firms that write only one usually satisfy none of the three audiences:
The client needs a brief narrative which links the goals, the time horizon, and the risk position to the recommendation, all expressed in simple language.
The advisor needs the contributing factors, alternatives considered, and scenarios under which the recommendation would change.
Compliance and audit need full technical reproducibility: inputs, feature attributions, rule and model versions, and the decision path.
Generative AI in wealth management has a specific, limited role here: rendering proven decision logic into readable language for the first two audiences. It should not invent an explanation after the fact: a model asked to justify an output it did not produce will generate a plausible rationale rather than the actual one — the most dangerous pattern in this domain, and the easiest to ship by accident.
Governance as Engineering, Not Policy
Model governance here means documentation, versioning, pre-deployment validation, drift monitoring, bias testing and periodic revalidation — engineering practice with named owners and records, not an annual policy exercise. Firms operating across jurisdictions must reconcile different regimes against one control set, the practical subject of AI governance in regulated industries, which works through the UAE, Saudi, and Qatar rulebooks in detail.
Validation and bias testing share one obstacle: the edge cases that matter most are rare in production data, and that data is sensitive. Generating synthetic data for AI testing lets firms stress models against low-frequency scenarios and protected-attribute combinations without exposing client records.
Two voluntary frameworks carry most of the operational weight, because they are what examiners and clients recognize: the NIST AI Risk Management Framework (AI 100-1) with its Generative AI Profile (AI 600-1, July 2024), and ISO/IEC 42001:2023, which became certifiable through accredited bodies once ISO/IEC 42006:2025 set the requirements for certification bodies. IOSCO’s Supervisory Toolkit for AI Use in Capital Markets (FR/02/2026, May 2026) sets out what supervisors will look for: governance and risk management, third-party and outsourcing risk, disclosure, and recordkeeping.
What the Rules Actually Require — and Do Not
Wealth management firms routinely over- or under-estimate their AI Act exposure, so the position is worth stating precisely. The EU AI Act (Regulation (EU) 2024/1689) classifies as high-risk, under Annex III point 5, AI systems used to evaluate the creditworthiness of natural persons — expressly excluding systems used to detect financial fraud — and AI systems used for risk assessment and pricing in life and health insurance. Investment advice, discretionary portfolio management and suitability assessment are not listed in Annex III and are not per se high-risk under the Act. Article 5 prohibitions and the Article 4 AI literacy duty apply, both in force since 2 February 2025; the Article 50 transparency obligations apply from 2 August 2026; and — decisively — existing sectoral conduct law. A firm that also scores credit or prices insurance falls under Annex III for those systems.
The high-risk timeline has moved. Regulation (EU) 2026/1744, the Digital Omnibus on AI, entered into force on 27 July 2026 and deferred the Chapter III high-risk obligations: Annex III stand-alone systems now apply from 2 December 2027, Annex I embedded systems from 2 August 2028. The Article 50 transparency duties were not deferred. Firms whose roadmaps assumed the original 2 August 2026 high-risk date have more runway than they planned for.
The UK took a different route. The FCA states in its approach to AI that it does not plan to introduce extra AI regulations, relying instead on existing frameworks — the Consumer Duty and the Senior Managers and Certification Regime. Its Mills Review (6 July 2026) found that 20% of surveyed consumers, around 11 million UK adults, said they were likely to use AI capable of acting autonomously within pre-set goals, with trust and control as the main constraints. In Singapore, MAS consulted on Guidelines on AI Risk Management between November 2025 and January 2026; final guidelines remain pending, and MAS issued an interim industry AI Risk Management Toolkit in March 2026.
The conclusion is consistent across jurisdictions: the binding constraints here are outcome-based conduct regimes already in force, not AI-specific statutes. A firm that can evidence suitability, supervision and best-interest outcomes under MiFID II, the Consumer Duty or Reg BI is substantially compliant; a firm that can will not be rescued by a model card.
Those same oversight requirements determine how far autonomy can reasonably be pushed.
Agentic AI in Wealth Management: From Copilots to Controlled Workflows
When a copilot receives a request, an agent breaks down a goal into steps, uses the various systems, and acts upon them with only limited supervision. In the field of wealth management, the distinction lies in accountability rather than in capability: an agent who updates a CRM record, requests a document, and schedules a review has carried out three actions which a supervisor must be able to reconstruct.
Interest is near-universal and deployment near-zero. EY-Parthenon’s 2025 survey of 100 wealth and asset management firms, weighted to the Americas, found 78% already exploring agentic AI, while just 7% of the asset managers surveyed had deployed it. Orion’s Fourth Annual Advisor Wealthtech Survey, covering 571 advisors in December 2025, found 73% of advisory firms using AI in some capacity but only 6% using agentic workflows. Two independent samples, one conclusion: adoption is broad and shallow.
FINRA’s 2026 Annual Regulatory Oversight Report, published in December 2025, explains why. Its GenAI section names the supervisory problems specific to agents: agents acting autonomously without human validation, agents acting beyond their intended scope, multi-step reasoning that is difficult to trace or explain, and persistent hallucination and bias risk. It recommends human-in-the-loop protocols and controls that limit agent actions.
That maps to a workable boundary. Agentic workflows suit reversible, internally-scoped, evidence-producing tasks — assembling meeting packs, chasing missing onboarding documents, reconciling data, drafting reports for review. Under current supervisory expectations, they do not suit anything that changes a client’s position, issues a recommendation, or communicates externally without approval. Three controls separate a pilot from a production system: a hard approval gate before any external or irreversible action; a complete log of each step, tool call, and intermediate output rather than only the final result; and a defined scope of authority per agent, enforced at the integration layer rather than in the prompt. All three are architecture decisions, which is why agentic AI rarely survives being bolted onto an existing stack.
Approval gates, step-level logging, and scoped agent authority are architecture decisions, not configuration.
AI Tools and Platforms for Wealth Management Firms
Firms evaluating top AI platforms for wealth management are usually choosing between four kinds of products rather than comparing like with like. An AI wealth management platform embedded in a portfolio system, a horizontal productivity assistant, and a point solution for meeting capture solve different problems and come from different budgets, which is why mixed shortlists stall.
The table below groups representative, currently-offered AI tools for wealth management by category. It is not a ranking, and the pricing column records only what each vendor publishes on its own site, checked in September 2026.
Platform | Category | Best for | Deployment/integration | Public pricing |
|---|---|---|---|---|
GenAI embedded in an institutional portfolio and risk platform | Natural-language querying of portfolio and risk data | Native to Aladdin; scoped so it will not give investment advice or answer outside platform boundaries | No | |
Industry CRM plus agentic layer | Client data as system of record, with configurable agents | SaaS CRM; agents configured on top, consumption-based credits | Yes — $325–$750 per user/month | |
Horizontal productivity AI | Drafting, summarization and meeting work across the document estate | Add-on requiring a qualifying Microsoft 365 plan | Yes — Business add-on from $18 per user/month, annual | |
Portfolio data and analytics with native AI | Multi-asset and alternatives analysis on a unified data layer | Native to Addepar; permission-aware, traceable outputs | No | |
Advisor meeting and workflow assistant | Pre-meeting prep, note-taking, follow-ups, audit-ready records | SaaS, 40+ two-way CRM, planning and conferencing integrations | Yes — from $100 per advisor/month | |
Privacy-first client intelligence assistant | Structured client data from conversations; form auto-fill | SaaS, two-way CRM and conferencing integrations; conversations not recorded | Yes — $67–$184 per user/month, annual | |
AI advanced planning (tax, estate, insurance) | Planning opportunities from tax returns, estate documents, and policies | SaaS, document-upload-driven; integrates with the planning stack | No — quoted on request |
Two things follow for selection. The categories divide on cost of entry: advisor-workflow tools publish per-seat prices a team can trial without an integration program, while platform-native and advanced-planning products quote on request — a signal of deal size and implementation effort, not sophistication. That split tracks where value sits. Meeting and document automation pays back fastest because it needs no connection to a system of record and carries limited regulatory exposure, but buying wealth management AI is rarely the hard part. The AI tools for wealth management that change advisory economics are the ones sitting on the firm’s own client data, and those are integration projects, not purchases.
The Data and Architecture Foundation for AI in Wealth Management
Every application above assumes the model can see a correct, current, permissioned view of the client. In most firms, it cannot: client details, portfolios, transactions, and documents sit across CRMs, custodial platforms, planning tools, spreadsheets, and legacy databases, with no shared identity between them. This explains the persistent gap between pilot and production results: a model that performs well against a curated dataset underperforms against a fragmented one, and no amount of prompt engineering closes that gap.
Most wealth management AI initiatives don’t stall because the language model is flawed; they stall because client data is fragmented across legacy silos. Generative AI is fundamentally an integration and architecture project, not a prompt engineering shortcut. Without a unified data layer with built-in audit trails and permission controls, you are simply putting a sophisticated interface over fragile data.


The Layers That Have to Exist
A workable architecture for generative AI for wealth management separates concerns that monolithic designs merge:
Data and identity — a single client view from KYC, AML, transaction, behavioral, and market data, with entity resolution, lineage, and privacy controls. Ownership, quality, and access rules here are the subject of data governance in banking, and they are prerequisites, not parallel work.
Risk profiling and features — separate models for capacity, tolerance and need, each calibrated and drift-monitored.
Decisioning — a rules engine enforcing policy guardrails and suitability checks, with an exceptions workflow that captures approvals.
Explainability — distinct outputs for client, advisor, and compliance, from feature attributions, counterfactuals, and rule overlays.
Evidence and auditability — automatic logging of inputs, outputs, rules, and versions, with immutable trails.
Monitoring and model risk — drift detection, bias checks, and outcome monitoring against complaints, rejections, and churn.
Product integration — API-first inference, interfaces that allow effective challenge, role-based access control, and any language model confined to explanation rather than decision.
Layers one and five are the ones firms most often defer and most often regret deferring, because retrofitting lineage and audit evidence onto a live system usually means rebuilding it. Security sits across all seven: generative AI in wealth management widens the surface, since prompts, retrieved context, embeddings, and logs all become places where client data can persist, so access control, encryption, and retention rules for model inputs and outputs are baseline requirements, not later hardening.
This isn’t a question of modeling, which is the reason why most AI and wealth management initiatives stall at the engineering and integration stages rather than at the data science stage.
Turning the Foundation into a Working System
Most wealth management AI programs fail in the same place: the model works in a notebook, the pilot shows value on clean data, and the project stops where it meets the firm’s real systems, permissions, and supervisory obligations. Before committing budget, establish whether a specific use case can reach production. An AI readiness assessment tests that across business case, data, process, systems, people, and governance, and readiness varies by use case rather than by organization.
At Lumitech, we work with financial institutions on exactly this layer. Our fintech software development services cover investment and wealth platforms, risk management and analytics systems, legacy modernization through an API-enabled layer, and KYC/AML automation, with PCI DSS, GDPR, PSD2, and SOC 2 requirements designed into the architecture rather than audited afterward. Our AI development services span RAG systems, intelligent document processing, agentic AI development, and MLOps — the components most AI use cases in wealth management are assembled from.
Two engagements bear on the problems above. We built SignalSigma, an analytics-driven investment platform for finance professionals and advisors, covering a portfolio dashboard, stock screener, strategy, and risk modules. And for a personalized financial platform comparing high-yield savings and CD rates across the German and US markets, we implemented universal single sign-on, live rate synchronization, and an AI-driven recommendation engine — cutting average onboarding time by 30%, reducing time-to-account-opening to under three minutes, and raising the likelihood of a client opening a second laddered CD by 45%. Neither is a wealth management engagement, and we claim no published AI-in-advice outcomes we do not have.
Conclusion
The firms that get value from AI in wealth management will not be the ones that adopt earliest. On current evidence, they will be the ones that pick problems where the work is documentary rather than judgmental, build the data and audit layer before the model layer, and keep a named human accountable for every regulated decision. The most durable AI in wealth management examples so far share that shape.
The honest position in late 2026 is that the operational case for AI wealth management is proven and the economic case is not. Adoption is broad, agentic deployment negligible, and half of sector CEOs report no measurable cost savings. That is not a reason to wait — the capacity constraints and client expectations driving this are real and worsening — but it is a reason to instrument your own AI wealth management program rather than budget against someone else’s projection.


